Canada's Banking Regulator Adjusts Capital Buffers to Support Economic Lending
The Office of the Superintendent of Financial Institutions lowers capital reserve requirements for major banks to encourage increased lending activity.
PENN Explainer
Hear this story explained in 90 seconds.
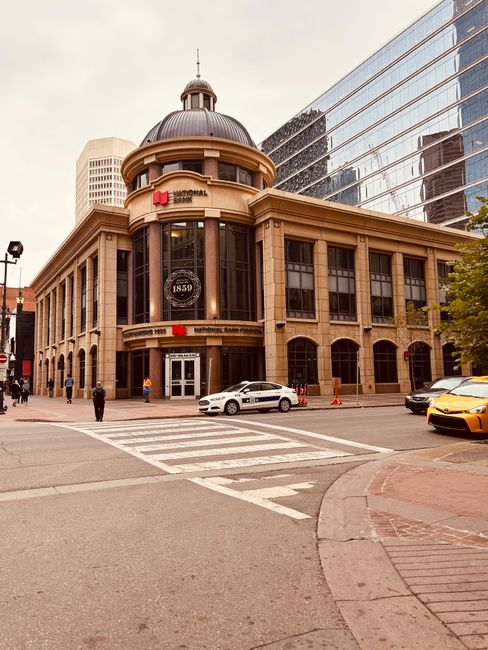
Canada's primary banking regulator, the Office of the Superintendent of Financial Institutions, announced a significant policy shift on June 19, 2026, to increase liquidity in the national economy. The regulator decided to lower the capital cushion that the country's six largest banks must hold in reserve. This move is expected to free up approximately $74 billion in excess capital for potential use in the broader financial system. The decision aims to provide banks with more flexibility to support lending activities during a period of shifting market conditions.
By reducing these requirements, the regulator intends to ensure that capital remains available for businesses and households across the country. The Domestic Stability Buffer, which applies to the nation's largest financial institutions, is reviewed regularly to ensure banks remain resilient against economic stress. While the buffer is typically adjusted to maintain stability, this latest reduction signals a strategic effort to encourage banks to deploy capital more actively. The regulator has indicated that it will monitor how these institutions choose to utilize the newly available funds.
Analysts are watching closely to see if this capital will be directed toward mortgage lending, commercial credit, or other corporate activities. The timing of this policy change coincides with a notable increase in the uninsured mortgage market. Recent data shows that uninsured residential mortgage funds advanced by over 40 percent year-over-year as of April 2026. With uninsured lending now representing a large majority of new residential mortgage activity, the banking sector faces unique pressures.
Households are currently navigating a cycle of mortgage renewals at higher interest rates than those seen in previous years. The regulator has maintained that despite these pressures, the capital positions of major banks remain strong enough to absorb potential financial stress. This assessment supports the decision to allow for a more flexible capital environment. The government has also implemented various mortgage reforms over the past two years to assist homeowners and first-time buyers.
These measures include adjustments to amortization periods and the removal of certain qualifying rate requirements for mortgage switches. These combined efforts reflect a broader strategy to balance financial stability with the need for accessible credit. Future developments will depend on how banks balance their risk management with the opportunity to expand their lending portfolios.
Ask the Author
Subscribers can ask the journalist a question about this story. Subscribe to ask.
Neutrality note
Auto-harvested from global news wires and presented neutrally by PENN.
to vote
Comments
No comments yet — be the first to share your thoughts.