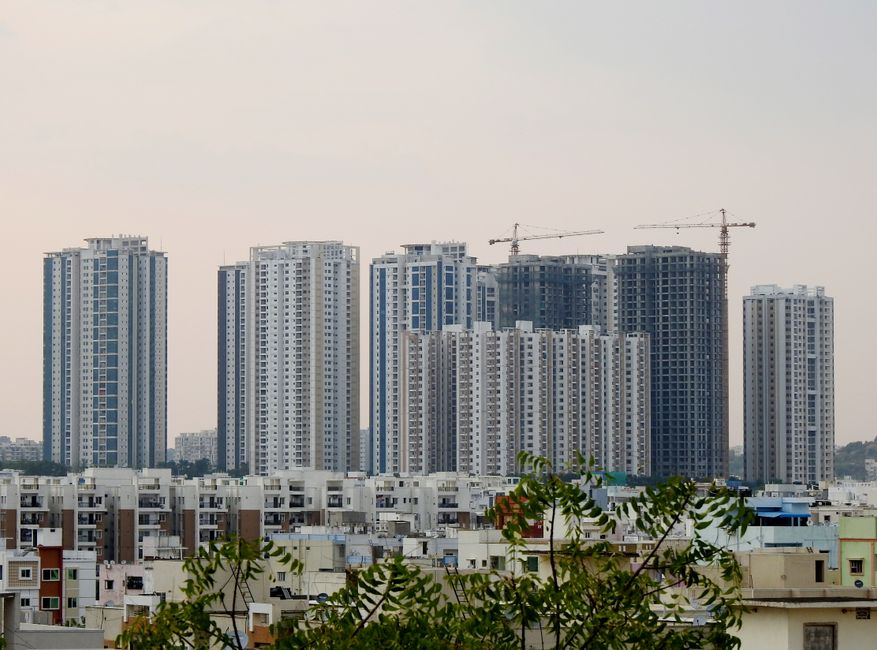
US Commercial Office Market Shows Signs of Recovery Amidst Persistent Distress
While national vacancy rates decline, central business districts continue to face significant challenges with distressed assets.

PENN Explainer
Hear this story explained in 90 seconds.
The United States commercial real estate sector is currently navigating a complex period of recovery and adjustment. Recent data from the second quarter of 2026 indicates that office vacancy rates have declined in 49 of 92 major markets across the country. This trend marks the second consecutive quarter of improvement, suggesting that leasing fundamentals are beginning to strengthen in a broader range of locations. Experts at Cushman & Wakefield note that this progress is spreading beyond just a few primary gateway cities, signaling a more widespread stabilization in the office market.
Despite these positive indicators, the sector remains under pressure from a significant volume of distressed assets. According to research from Yardi, distressed office transactions have accounted for 34.6% of all deals in central business districts since 2024. This represents a dramatic increase from the 6.2% rate observed between 2021 and 2023. These figures highlight a sharp divergence between general market health and the specific difficulties facing older or less competitive office properties in urban cores.
Market analysts, including Omar Eltorai and Cole Perry of the Altus Group, have observed that the recovery looks different beneath the surface of national headlines. While transaction activity is increasing and pricing is showing an upward trend, investors are becoming increasingly selective. There is a clear shift in preference toward larger, higher-quality assets that can better compete in a changing work environment. This flight to quality is leaving older, less efficient buildings at a disadvantage, contributing to the ongoing distress in certain segments.
One factor contributing to the tightening of office supply is the active removal of obsolete buildings from the market. Developers and property owners are increasingly pursuing conversions, which reduce the total inventory of available office space. By repurposing these structures for other uses, the industry is helping to balance supply with current demand levels. This strategy is viewed as a necessary step in modernizing the urban landscape and addressing the surplus of outdated office space.
Financial pressures continue to influence the broader real estate landscape as well. Higher interest rates have created a challenging environment for refinancing, leading some lenders to offload troubled loans at a loss. This process of price discovery is essential for the market to move forward, though it remains a difficult period for many property owners. As the industry works through these financial hurdles, the focus remains on long-term sustainability and income-generating potential.
Looking ahead, the outlook for the remainder of 2026 remains cautiously optimistic. Reports from firms like CBRE suggest that while economic challenges persist, there is potential for significant investment growth in specific sectors. The recovery is expected to be uneven, with different property types and geographic regions experiencing varying levels of success. Investors are closely monitoring these trends to identify opportunities in a market that is still finding its new equilibrium.
Retail and senior housing sectors are currently being highlighted as areas with strong potential for returns through 2030. These segments are benefiting from demographic shifts and changing consumer behaviors that support steady income streams. In contrast, the office sector continues to be a point of focus for analysts who are watching how companies adapt their physical footprints to hybrid work models. The ability of office properties to offer modern amenities and flexible spaces will likely determine their future value.
Public policy and economic conditions will continue to play a major role in shaping the real estate environment. As interest rates stabilize and the economy adjusts, the market is expected to become more predictable for developers and investors alike. The current period of transition is seen by many as a necessary phase of correction that will ultimately lead to a more resilient and efficient commercial property market. Stakeholders are encouraged to remain adaptable as these trends continue to unfold throughout the year.
Ask the Author
Subscribers can ask the journalist a question about this story. Subscribe to ask.
Nota de neutralidad
Auto-harvested from global news wires and presented neutrally by PENN.
to vote
Comments
No comments yet — be the first to share your thoughts.